A bank loan versus online lender decision can determine whether you get capital in time to buy inventory, repair a vehicle, cover payroll, or take on a new contract. The right option is not automatically the one with the lowest advertised rate. It is the financing that your business can realistically qualify for, use productively, and repay on terms that fit its cash flow.
For many small-business owners, a bank is worth considering when time is not urgent and credit is strong. An online lender can make more sense when traditional approval standards are standing in the way, the opportunity cannot wait weeks, or your business needs a more flexible structure. Knowing the trade-offs helps you move forward without wasting time on financing that was never a fit.
What a Bank Loan Usually Requires
Traditional banks generally offer term loans, lines of credit, commercial real estate loans, and equipment financing. Their rates can be attractive, particularly for established companies with strong personal credit, stable revenue, healthy cash reserves, and substantial documentation.
That lower rate often comes with a slower, stricter process. A bank may want multiple years of business and personal tax returns, financial statements, debt schedules, bank statements, collateral information, and a clear explanation of how the money will be used. Underwriting can take several weeks or longer, especially when the request is complex.
Banks also tend to favor borrowers who fit a narrow credit profile. A recent credit issue, a short operating history, uneven seasonal revenue, or high existing debt can lead to a decline even when the business has real sales and a legitimate need for capital. A rejection is frustrating, but it does not necessarily mean your business has no financing options.
When a Bank Can Be a Strong Choice
A bank loan may be the right move if your business has time to wait, has a strong credit history, and can provide detailed financial records. It can work especially well for a long-term investment with predictable returns, such as purchasing commercial property or financing a major expansion planned far in advance.
The key question is whether your business fits the bank’s approval box today. If it does, a traditional loan may provide a low-cost source of capital. If it does not, repeatedly applying at banks can create delays while the business need keeps growing.
How an Online Lender Works
An online lender uses digital applications and alternative underwriting methods to assess a business. Instead of looking only at a credit score and annual tax returns, many online financing providers also evaluate current revenue, recent bank activity, time in business, invoices, equipment, or other signs of operating strength.
That approach can create more access for owners with fair or challenged credit. It may also speed up the decision process. Depending on the product and lender, an applicant can receive a pre-approval decision quickly and move toward funding faster than through a conventional bank process.
Online lending is not one product. A term loan can provide a lump sum for a defined project. A business line of credit can support recurring working-capital needs. Revenue-based financing may be useful when sales fluctuate and repayment needs to align more closely with business performance. Equipment financing can help preserve cash while acquiring trucks, machinery, technology, or other essential assets.
Speed and flexibility can carry a higher cost than a prime bank loan. Some products have higher interest rates, shorter terms, origination fees, or repayment schedules that require close attention. That does not make them a bad choice. It means the financing should be measured against the expected return from the purchase or opportunity.
Bank Loan Versus Online Lender: The Real Differences
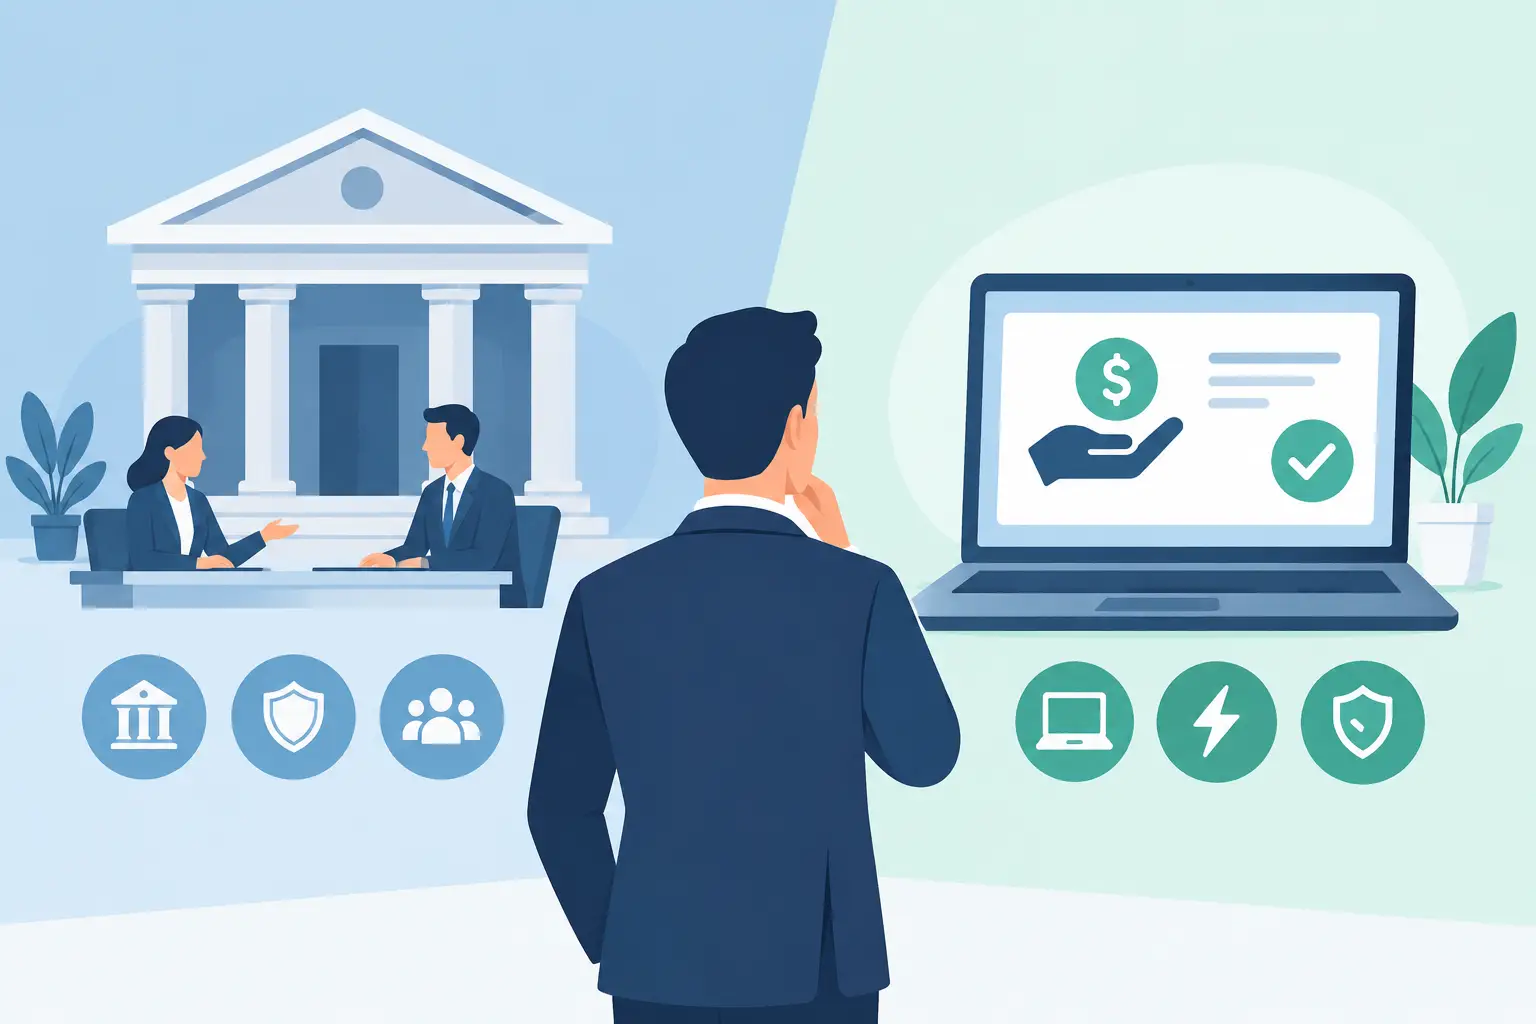
The clearest difference between a bank loan versus online lender is not simply the application itself. It is how each provider weighs risk. Banks often prioritize credit history, collateral, and extensive financial documentation. Online lenders may place more weight on recent revenue, cash flow, and the business’s ability to support payments now.
A bank may offer better pricing to a highly qualified borrower but require more time and impose tighter qualification standards. An online lender may offer faster decisions and wider eligibility but charge more for that access and speed. Neither path is automatically better. The right choice depends on your business’s profile, timeline, and purpose for the funds.
Repayment structure matters just as much as the stated rate. A lower-rate loan with a payment that strains monthly cash flow can create problems. A higher-cost option used to purchase profitable inventory before a busy season may be sensible if the added margin exceeds the financing expense. Before accepting an offer, look at the total repayment amount, fees, payment frequency, term length, and whether early payoff is allowed or rewarded.
Approval Speed Is a Business Issue
If a refrigeration unit fails at a restaurant, a truck needs repairs, or a supplier discount expires this week, waiting a month for a bank decision may cost more than the difference in financing cost. Fast funding is not a luxury when it protects revenue, customer relationships, or an important contract.
On the other hand, if you are planning a renovation six months from now, you may have room to pursue bank financing first. Your timeline should guide the process. Do not treat a slow approval path as a free option when delayed capital could interrupt operations.
Credit Is Important, but It Is Not the Whole Story
Personal and business credit affect your options, but they are not the only measures of a viable company. Many owners have credit challenges tied to a past slowdown, medical expenses, a startup period, or a temporary cash-flow disruption. A business that now has consistent deposits, customers, and a clear capital need may still qualify for financing through the right lender.
This is where a lender network can help. Rather than relying on one bank’s underwriting rules, Bad Credit Business Loans connects applicants with more than 75 lending partners that consider different combinations of credit, revenue, time in business, assets, and funding purpose. Eligibility may begin with a 550+ credit score and at least one year in business, although final approval and terms always depend on the lender and the full application.
Choose Financing Based on the Job It Must Do
Start with the purpose of the funds. A one-time equipment purchase may call for equipment financing because the asset helps secure the transaction and the repayment term can match its useful life. Inventory for an upcoming sales cycle may fit a short-term loan or revenue-based option. Ongoing gaps between paying vendors and collecting from customers may point to a line of credit or asset-based financing.
Next, calculate what the capital is expected to produce. If $50,000 in inventory is likely to generate $85,000 in sales at a healthy margin, determine how much profit remains after product costs, operating expenses, and financing charges. If the numbers do not leave enough room, borrowing may add pressure rather than solve a problem.
Finally, be honest about your timeline and documents. A business with excellent credit and complete financials may benefit from pursuing a bank. An owner who needs working capital quickly, has a 620 score after a tough year, or cannot meet a bank’s collateral requirements may be better served by exploring online options at the same time.
Prepare Before You Apply
A clean application can improve your chances and help lenders evaluate your request faster. Have your recent business bank statements, basic revenue information, business formation details, photo identification, and a clear explanation of how much capital you need and why. If you are financing equipment, gather the quote or invoice. If you are using funds for expansion, be ready to explain the projected revenue impact.
Avoid borrowing more than the plan requires just because a larger amount is available. Also avoid accepting an offer without understanding the full payment schedule. Ask whether payments are daily, weekly, or monthly, how total payback is calculated, and what happens if revenue slows. Clear answers are part of a responsible financing decision.
Your business should not have to pause because one bank said no. Secure an instant pre-approval, compare the terms that fit your actual cash flow, and choose capital that gives your next move a real chance to pay off.