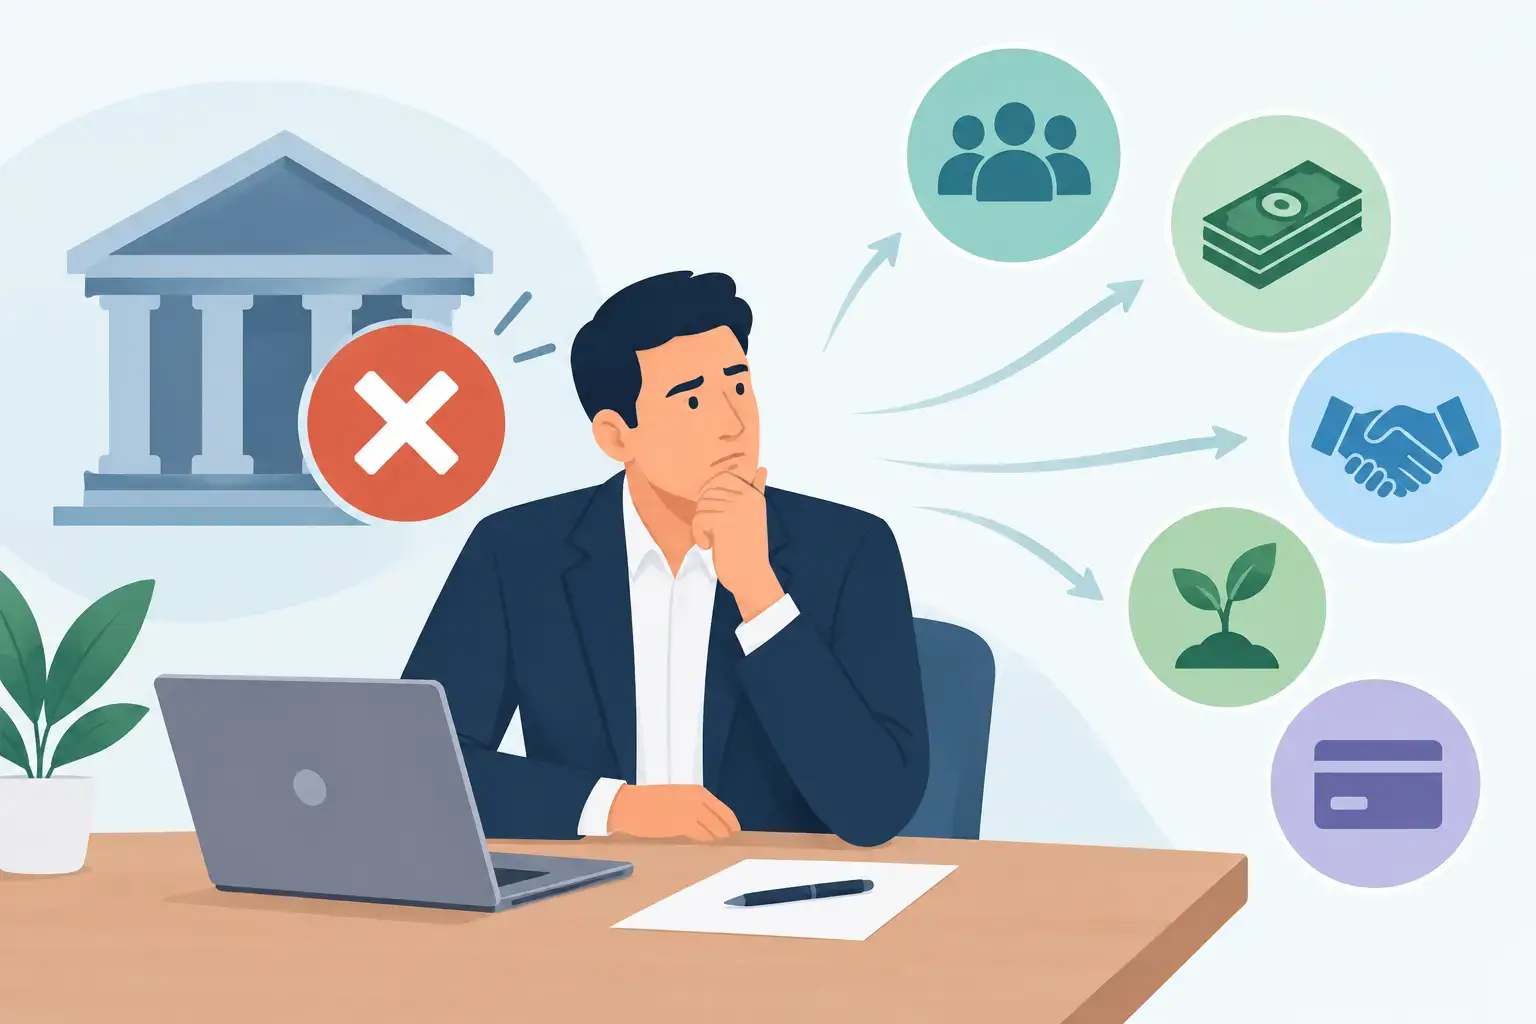
A bank denial can feel personal, especially when you need money for payroll, inventory, a truck, or a project already on the calendar. But a declined application does not mean your business has no path to capital. There are practical options after bank denial that look beyond a single credit score and focus on your revenue, time in business, equipment, invoices, and purpose for funding.
The right next step is not applying everywhere at once. It is identifying why the bank said no, matching that reason to a financing structure, and protecting your cash flow while you move forward.
Why Banks Deny Business Loan Applications
Traditional banks tend to use strict approval standards. A denial may be tied to personal or business credit, limited collateral, inconsistent revenue, a high existing debt load, or a short operating history. Some banks also have narrow industry preferences or require financial documentation that many growing businesses do not yet have organized.
A denial can also be a mismatch rather than a judgment on your business. For example, a profitable contractor may need a fast vehicle purchase, but a conventional bank loan can take weeks and require tax returns, financial statements, and collateral review. A restaurant with steady card sales may need inventory funding before a busy season, while the bank wants stronger cash reserves.
Before seeking another option, ask for the reason behind the decision if the bank will provide it. That information can help you avoid repeating the same application with the same result.
7 Options After Bank Denial
1. Revenue-Based Financing
Revenue-based financing provides a lump sum of working capital that is repaid through a percentage of future sales or through scheduled payments tied to your business revenue. It can be a fit for businesses with regular card transactions, deposits, or sales volume that need capital quickly.
This option may help cover payroll, inventory, marketing, repairs, or a short-term expansion opportunity. Approval often places more weight on recent revenue performance than a traditional bank does. The trade-off is that the cost of capital can be higher than a conventional bank loan, so it is best used when the expected business return clearly supports the payment.
2. A Business Line of Credit
A business line of credit gives you access to a set amount of capital that you can draw from as needed. Instead of taking one large loan all at once, you use the funds for operating expenses and repay what you borrow, often with the ability to draw again.
This structure works well for uneven cash flow. A retailer may use it to buy inventory before a seasonal rush. A service business may use it to cover payroll while waiting for customer payments. Lines of credit can range from bank-issued products to alternative financing options with more flexible credit requirements.
Review whether the line has draw fees, maintenance fees, minimum payments, or a fixed repayment period on each draw. Flexibility is valuable, but the terms still need to fit your monthly cash flow.
3. Equipment Financing
If the money you need is tied to a specific asset, equipment financing can be more practical than an unsecured business loan. The equipment itself may serve as collateral, which can make this option more accessible for owners with challenged credit.
Common uses include work trucks, trailers, medical equipment, restaurant equipment, construction machinery, manufacturing tools, and business technology. Rather than using working capital to pay cash upfront, you make scheduled payments while putting the equipment to work in the business.
The key question is whether the asset will generate revenue, reduce costs, or increase capacity enough to justify the payment. A landscaper adding a mower that lets the crew complete more jobs is different from buying equipment that will sit idle for half the year.
4. Asset-Based Financing
Asset-based financing uses business assets to support the financing request. Depending on the lender and the business, eligible assets may include equipment, vehicles, inventory, accounts receivable, or other property with measurable value.
This can be a useful route when your credit profile is not your strongest qualification point, but your business owns assets or has valuable receivables. Transportation companies, wholesalers, manufacturers, and contractors often have assets that can help support a financing decision.
Because the asset secures the financing, understand exactly what is pledged and what happens if payments are missed. This option can provide meaningful access to capital, but it requires a clear repayment plan.
5. Invoice Financing or Receivables Funding
Waiting 30, 60, or 90 days for customer payments can create a serious cash-flow gap. Invoice financing allows eligible businesses to access capital against unpaid invoices rather than waiting for customers to pay in full.
It is often a strong fit for B2B companies that bill established customers, including staffing firms, trucking companies, distributors, contractors, and professional service businesses. The strength of your customers’ payment history may matter as much as your own credit profile.
This is not the right solution for every business. It works best when invoices are legitimate, completed work is clearly documented, and customer payment terms are reliable. Still, for businesses with money tied up in receivables, it can turn earned revenue into usable operating capital.
6. Short-Term Business Financing
Short-term financing is designed for immediate needs with a shorter repayment timeline than a standard term loan. It can help when a time-sensitive opportunity cannot wait, such as a bulk inventory discount, emergency repair, tax obligation, or a deposit required to take on a larger job.
Speed is the main advantage. The downside is that frequent payments may put pressure on cash flow, particularly for businesses with thin margins or inconsistent sales. Before accepting an offer, calculate the actual payment schedule and make sure your business can handle it during a slower week or month, not just at peak revenue.
Short-term funding is usually most effective when it supports a defined, near-term return. Use it to solve a clear business problem, not to repeatedly cover an ongoing operating loss.
7. A Term Loan Through a Broader Lender Network
A business term loan provides a lump sum repaid over a set period. While banks are one source of term loans, they are not the only source. Alternative lenders may consider a wider range of factors, including revenue trends, industry, time in business, and the reason you need capital.
For many established owners, this is one of the most useful options after bank denial because it can finance a planned investment without requiring the narrow profile a conventional bank expects. Term loans may be used for expansion, renovations, hiring, inventory, consolidation of qualifying business obligations, or working capital.
Terms and pricing vary widely. Compare the total repayment amount, payment frequency, early payoff policy, collateral requirements, and whether a personal guarantee is required. A lower monthly payment is helpful only if the total cost and term make sense for your business.
How to Choose the Right Funding Option
Start with the use of funds. Equipment financing may make more sense for a vehicle or machine than using a general working capital product. Invoice financing may fit unpaid receivables better than taking on a long-term loan. A line of credit can be more useful than a lump sum when you need flexibility for recurring expenses.
Then look at your repayment source. If repayment will come from a new contract, estimate when the revenue will actually arrive, not when you hope it will arrive. If the financing supports inventory, factor in how long it takes to sell that inventory and collect payment.
Finally, compare offers based on the complete structure. Do not focus only on the approval amount. The right offer is one that provides enough capital, has payments your business can sustain, and supports a purpose that improves your operating position.
Strengthen Your Next Application
A bank denial is also a chance to tighten your financial profile. Keep business bank statements organized, separate personal and business spending, track monthly revenue, and address errors on your credit reports. Paying current obligations on time and reducing high revolving balances can improve future options as well.
You do not need perfect credit to pursue business funding. Many lenders serve established businesses with a 550+ credit score, at least one year in business, and a demonstrated ability to generate revenue. Requirements depend on the financing product, industry, and lender, so presenting accurate information matters.
If you need capital now, a lender-matching process can help you evaluate multiple paths without treating one bank’s decision as the final answer. Bad Credit Business Loans connects qualified owners with a network of 75+ lending partners for financing based on real business conditions, not credit alone.
A denial is a signal to choose a better-fit funding route, not a reason to put your plans on hold. Secure an instant pre-approval, review the terms carefully, and put capital toward the next move that keeps your business earning.