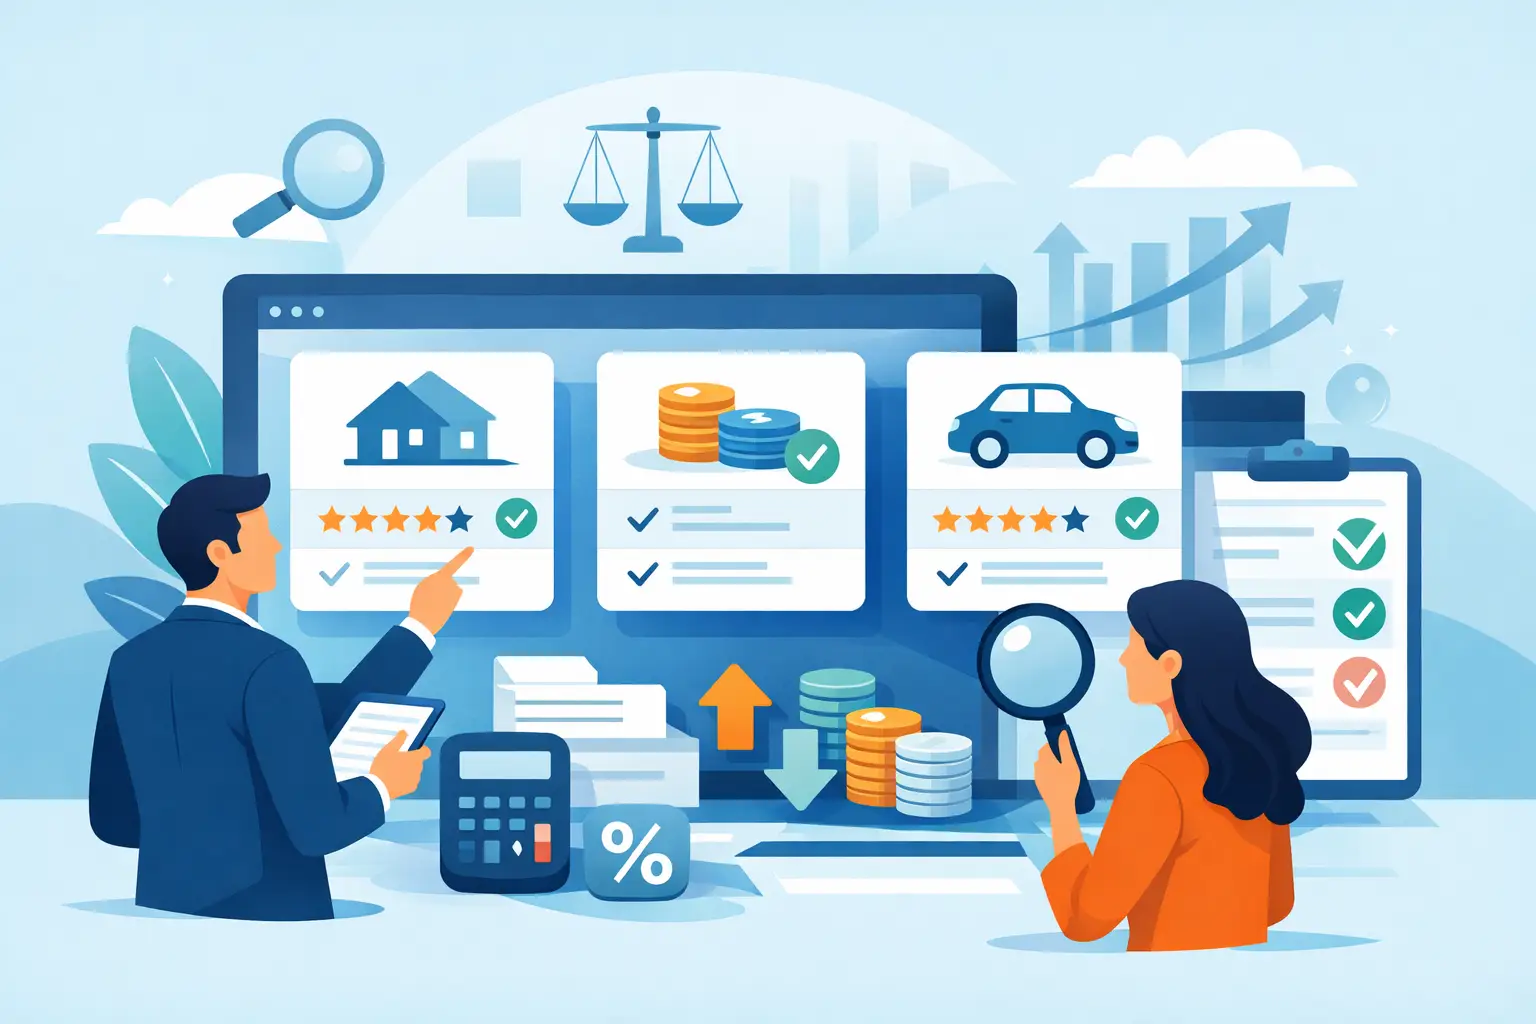
A funding offer can look great until the payment schedule, fees, and payoff terms show up. That is why lender marketplace reviews deserve more than a quick glance at a star rating. For a business owner who needs working capital, inventory, equipment, or money for an expansion, reviews can reveal whether a marketplace communicates clearly, presents realistic options, and follows through after you apply.
A marketplace is not the same as a direct lender. It connects applicants with potential lending partners, often giving business owners access to multiple financing structures through one application. That can be useful when a bank has already said no because of credit history, limited collateral, or a business profile that does not fit its rules. But it also means you need to evaluate both the marketplace experience and the offer from the individual lender.
What lender marketplace reviews can tell you
The most useful reviews describe the process, not just the outcome. A five-star review that says only “great service” is encouraging, but it does not tell you whether the business owner understood the repayment terms or received funds when promised. Look for details about how quickly the applicant received a response, whether the representative explained the options, and whether the final terms matched the discussion.
Pay close attention to patterns. One negative review may reflect a misunderstanding or an applicant who did not meet a lender’s requirements. Repeated complaints about surprise fees, excessive pressure, unclear payment frequency, or poor communication deserve more weight. The same goes for repeated positive comments about responsive service and clear explanations.
Reviews are also helpful for setting realistic expectations. A legitimate financing marketplace should not make every applicant expect approval for every amount. Responsible providers assess revenue, time in business, credit, existing obligations, assets, and the purpose of the capital. If reviews suggest applicants were given straightforward answers, even when an offer was not a fit, that is generally a better sign than promises that sound too easy.
Separate the marketplace from the lender
When reading lender marketplace reviews, determine who the reviewer is actually talking about. Was the experience with the company that took the application, the lender that issued the funds, or a third-party servicing company handling payments? These roles can be different.
A marketplace should make that distinction clear before you accept an offer. You should know the name of the lender, the financing product, the amount funded, the payment amount or percentage, the payment frequency, the total cost, and any conditions tied to the agreement. If a reviewer says the experience changed after funding, look for whether that concern involves servicing rather than the original matching process.
This matters especially with fast financing. Speed can help when payroll is due, a truck needs repair, or a supplier requires a deposit. It should not replace a clear review of the agreement. A business owner can value quick funding and still ask direct questions before signing.
Check for specifics behind the star rating
A rating is a starting point, not a verdict. Read recent reviews first, then compare them with older ones. Companies can change their processes, partner networks, customer service teams, or product mix over time. A current pattern is more relevant to your application than a compliment from several years ago.
Look for these practical details in the reviews and in the marketplace’s own communication:
- Whether terms, payments, and fees were explained before the applicant signed.
- Whether the company asked reasonable questions about business revenue, operating history, and capital needs.
- Whether the reviewer understood the type of funding received, such as a term loan, line of credit, equipment financing, or revenue-based financing.
- Whether funding timing matched what was represented after all required documents were submitted.
- Whether customer service remained available when the applicant had questions about the offer or next steps.
Specific comments carry more value than emotional comments alone. For example, “My representative explained that payments would be weekly and reviewed the payoff amount before I accepted” is more useful than “They were amazing.” On the other hand, “I was told one thing and charged another” should prompt you to ask exactly what terms will be documented in writing.
Watch for red flags before you apply
No review platform is perfect. Some reviews are brief, some are disputed, and some may not reflect the typical customer experience. Still, certain warning signs should slow you down.
Be cautious if a company guarantees approval without reviewing your business information. Be equally cautious if you cannot get clear answers about the cost of financing, how often payments are due, or what happens if you pay early. A professional marketplace should be able to explain the product in plain English, even if final pricing depends on underwriting.
Also watch for pressure tactics. A legitimate offer may have a time limit because rates, lender capacity, or business conditions change. That is different from being told to sign immediately without enough time to read the agreement. You are making a business decision that can affect cash flow for months or longer. Ask for the terms, review them, and make sure the payment fits your operating budget.
Be careful with reviews that focus only on being approved. Approval is valuable, particularly for owners with fair or challenged credit, but it is not the only goal. The financing needs to solve a real business problem without creating an unmanageable payment. A smaller amount with workable terms can be more useful than a larger offer that strains daily or weekly cash flow.
Compare offers by business impact, not just rate
A marketplace may provide more than one option. That is where the value of a broad lending network can show up, especially when your credit profile does not meet conventional bank standards. Compare each offer based on how it affects your business, not only on the advertised rate or funded amount.
Start with the purpose of the capital. Equipment financing may make sense when the equipment itself supports the transaction. A line of credit can be useful for recurring expenses and short-term cash gaps. A term loan may be a better fit for a defined project with a clear payoff timeline. Revenue-based financing may offer a different structure for a business with consistent card sales or deposits, but you need to understand how repayments change with revenue and how that affects your margins.
Then calculate the real payment obligation. Ask whether payments are daily, weekly, or monthly. Ask for the total amount you will repay and whether there are origination fees, closing costs, documentation fees, or early payoff policies. If the financing is tied to revenue, ask how the collection method works and how it could affect a slow month.
The right offer depends on your business. A contractor purchasing a work vehicle has different needs from a restaurant covering a seasonal inventory purchase. The best marketplace is not necessarily the one with the loudest approval promise. It is the one that helps you see the available options clearly and choose a structure your business can support.
Questions to ask after reading reviews
Reviews can help you prepare, but they cannot replace your own conversation with a funding specialist. Before you submit an application or accept an offer, ask how many lenders may review your request, what information is shared, and whether an initial review affects your credit. Ask what minimum qualifications apply and whether your industry, revenue, time in business, and credit profile are likely to fit the available programs.
If you receive an offer, ask for a direct explanation of the repayment schedule, total repayment amount, fees, collateral or personal guarantee requirements, and what documents you will sign. If an answer is vague, ask again. Clear communication before funding is one of the strongest signs that you are working with a provider that respects your business.
For owners who have been turned down by banks, a marketplace can create access to options that a single lender cannot provide. Bad Credit Business Loans connects qualifying business owners with 75+ lending partners and considers applicants with a 550+ credit score and at least one year in business. The goal is not to force every owner into the same product. It is to identify funding that matches the business’s revenue, assets, operating history, and immediate need.
Use reviews to narrow your choices, then let the written offer make the decision. When the terms are clear and the payment supports the work you need to do next, you can move forward with more confidence.